
How Do You Get Your Name Off the Mortgage After a Divorce in Colorado?

By Jimmy Everetts, Mortgage Loan Originator, NMLS #1719458 · Published October 27, 2026
A divorce decree or a quitclaim deed doesn't take your name off a mortgage. Your name comes off when the loan is refinanced into one person's name, when the home is sold and the loan is paid off, or when the lender formally releases you after the other person assumes the loan.
Colorado's own separation agreement form says so. The "Important Debt Notice" on form JDF 1115 explains that joint debt, including a home loan, stays joint "until it is fully paid or refinanced under just one of your names," and that even if your name comes off the title, "the lender is not required to release you from the debt."
The good news: there are more options than most people expect, and some of them can start before the divorce is final. Here's how each one works.
Not necessarily. Most mortgages let the lender call the loan due when the home changes hands. Federal law makes exceptions for homes with one to four units, including a transfer "resulting from a decree of a dissolution of marriage, legal separation agreement, or from an incidental property settlement agreement" that makes the borrower's spouse an owner.
So moving the house to one spouse in a divorce doesn't, by itself, let the lender demand the loan be paid off. Some couples choose to leave the existing loan in place for a while, especially when its rate is better than what's available today.
That choice has a tradeoff worth weighing on purpose: you both stay on the loan, it stays on both credit reports, and you're counting on the other person to make every payment.
Three things:
On an FHA loan, HUD's notice to homeowners says you remain liable "unless you obtain a release from liability from your mortgagee," and that you "should ask for it if the mortgagee does not provide it to you automatically." Once you have it, keep a copy.
On a VA loan, federal law allows VA to release the original borrower when the loan is current and the person taking it over qualifies on credit and takes on all of the loan's obligations.
Conventional loans usually go the refinance route. If your conventional loan has a rate worth keeping, ask your loan servicer whether an assumption or release is possible. That decision is theirs.
If your ex takes over your VA loan, the entitlement you used stays tied to it until one of two things happens: the loan is paid in full, or a qualifying veteran assumes the loan and agrees to use their own entitlement in place of yours.
That matters if you plan to buy again with your VA benefit. Bring it up early and we'll map out what you'll have available for your next home. Our VA loan guide explains how entitlement works.
If you're keeping the home and paying your ex for their share, Fannie Mae treats that buyout as a limited cash-out refinance rather than a cash-out refinance when three conditions are met:
The second condition is the one most often missed: an agreement that awards the house but says nothing about where the refinance money goes. We'll walk you through what this means for your numbers.
Often, yes. Fannie Mae's buyout rule calls for a written agreement signed by everyone, not specifically a final decree. For alimony or child support you'll receive, Fannie Mae accepts a separation agreement when the divorce isn't final yet.
Plan around the court's timeline too. Colorado's court instructions say you must wait 91 days after filing the petition and serving the other spouse. The clock starts when you file together, or when the other spouse is served or signs a waiver. Other loan programs and lenders can have stricter rules, so check with us before you set a date.
If your decree or separation agreement assigns the old mortgage to your ex, Fannie Mae says the lender isn't required to count that payment in your monthly debts, even though you're still on the loan. The payment history from before the assignment still counts. And because your name stays on that loan until it's refinanced, paid off or released, its payments keep showing on your credit.
Support counts in both directions. Alimony or child support you receive can count as income when it's documented and expected to continue for at least three years. Support you're required to pay for more than ten months counts as a monthly debt.
If you're hoping to buy soon, talk with us before you settle on a price range. Our post A Fresh Start: What to Expect When Buying a Home After Divorce covers the next purchase in more detail.
Here's what we look for in the file. Your attorney decides the wording.
No. A quitclaim deed changes who owns the home. The mortgage is a separate contract, and you stay on it until it's refinanced, paid off or the lender releases you.
Possibly. Both can be assumed by someone who qualifies. Ask the loan servicer for the written release of liability as part of the assumption.
Under Fannie Mae's rules, at least 12 months of joint ownership before the new loan funds.
Often, with a written agreement signed by both of you. Programs differ, so confirm with your lender first.
When the loan is paid in full, or sooner if a qualifying veteran assumes the loan and substitutes their own entitlement.
Every divorce is different, and the right move depends on your loan, your timeline and what you want next. Call Jimmy at 720-979-8742 or book a time to talk. It costs nothing to talk it through. Questions about dividing property or what belongs in your agreement are for a Colorado family law attorney.
Please don't email or text tax returns, pay stubs or bank statements. We'll send you a secure upload link.
Sources checked October 27, 2026.
Jimmy Everetts, Mortgage Loan Originator, NMLS #1719458. Edge Home Finance, LLC, NMLS #891464. Lakewood, Colorado. 720-979-8742
This article is general information for Colorado consumers. It is not a commitment to lend or a guarantee of approval. Program requirements change; check with a licensed loan officer. Equal Housing Opportunity.
Page two looks like a phone bill, so most people file it unread. It's the only page where lenders actually differ — and three rules decide which numbers can move.

A rental gets financed under a different rulebook than the house you live in. Four things change, and the ones that surprise people are worth knowing before you start looking.
You sent everything. Two weeks later they want the same bank statement again. There's a rule underneath almost every re-ask — including one clock that runs to a date nobody tells you about.
The score your lender pulls isn't the one in your banking app. Here's what actually moves in 90 days, what quietly works against you, and the one date on your credit card statement that decides what gets reported.
Family help only counts if it's documented the way your loan program requires. Who can give it, what the gift letter needs, and why the order matters.
Business owners get told they don't make enough all the time — usually because the lender is reading a different number than they are. Here's which one.
Everything you need to know about buying a condo right now and what to look out for.
Buying a home from a family member? A gift of equity may allow an eligible seller to use some of the equity already in the home to help with your down payment and certain closing costs. Learn how it works and why planning ahead matters.
Thinking about buying a home after divorce? Learn what to expect, how divorce may affect your mortgage, and why understanding your options early can help you move forward with confidence.
If you're eligible for a VA loan, should you always use it? Learn why some veterans compare conventional financing, when it may make sense, and why the best mortgage depends on your financial goals—not just your eligibility.

Learn how mortgage contingencies and financing deadlines work, how they may affect earnest money, and what Colorado buyers should consider before limiting an important contract protection.

Should you pay upfront to lower your mortgage interest rate? Learn how mortgage discount points work, how to calculate your break-even point, and when buying points may—or may not—be the right financial decision.
A successful home purchase is about more than finding the right property. Learn why having a thoughtful strategy—and a team that helps you understand your options—can make a meaningful difference throughout the buying process.
Wondering if your mortgage pre-approval expires? Learn how long a pre-approval typically lasts, when updates are needed, and what changes could affect your eligibility.
Many Veterans know the basics of the VA loan program, but few realize just how flexible the benefit can be. Here are some of the most common surprises Veterans discover when they take a closer look at their home loan options.
Most buyers focus on the house itself during a showing, but the factors that determine long-term happiness often have little to do with countertops, paint colors, or staging. Learn how experienced buyers evaluate a home beyond first impressions and what really matters after move-in day.

What is the VA funding fee, why does it exist, and who has to pay it? Learn how VA funding fees work and why they help support one of the strongest loan programs available.
What is a 2-1 buydown, and is it actually worth it? Learn how temporary buydowns work, their pros and cons, and what buyers should consider before using one.
What do homeowners regret most after buying a home? From stretching budgets too far to overlooking long-term lifestyle needs, here are the lessons many buyers wish they knew earlier.
Two buyers can purchase the same home and end up with very different monthly payments. Here’s why—and what it means for your buying strategy.
FHA loans offer flexibility for first-time buyers—but they’re not one-size-fits-all. Learn how they work, their benefits, and what to consider before choosing this option.

First-time homebuyer programs aren’t just about getting into a home—they’re about doing it strategically. Learn how these programs work, who they’re for, and how they can help you buy with confidence.

You’ve built equity in your home—but what does that actually mean for you? Learn the smartest ways to use (or not use) your equity and how to decide what makes sense for your situation.

Thinking about using your 401(k) for a down payment? It’s possible—but it comes with trade-offs. Here’s what homebuyers should understand before tapping into retirement savings.
Your tax refund could be more useful than you think when preparing to buy a home. From boosting your down payment to paying off debt and improving your debt-to-income ratio, here are smart ways buyers use their tax refunds to strengthen their mortgage approval.
Many homebuyers assume student loans automatically prevent them from qualifying for a mortgage. In reality, lenders evaluate several factors beyond just the loan balance. Here’s what actually matters when applying for a home loan with student debt.
If you’ve served our country, you’ve earned more than a handshake. A VA home loan can be one of the most powerful benefits available to eligible veterans, active-duty service members, and surviving spouses. Here’s how it works — and what to know before you use it.
HOA fees are common in the Denver metro area — especially with condos and townhomes. Here’s what buyers should know about costs, rules, financial health, and how HOAs can impact your mortgage approval.
Thinking about upgrading but don’t want to give up your low interest rate? Here’s what happens to your mortgage if you move and keep your current home as a rental — including occupancy rules, qualifying for your next loan, and how rental income can offset your current payment.

Property taxes can feel confusing and stressful, especially when they change. Here’s a clear, no-panic breakdown of how property taxes really work and what homeowners should expect.

From accepted offer to closing table, here’s what really happens during the home-buying timeline — and how the right lender can help you close faster without cutting corners.
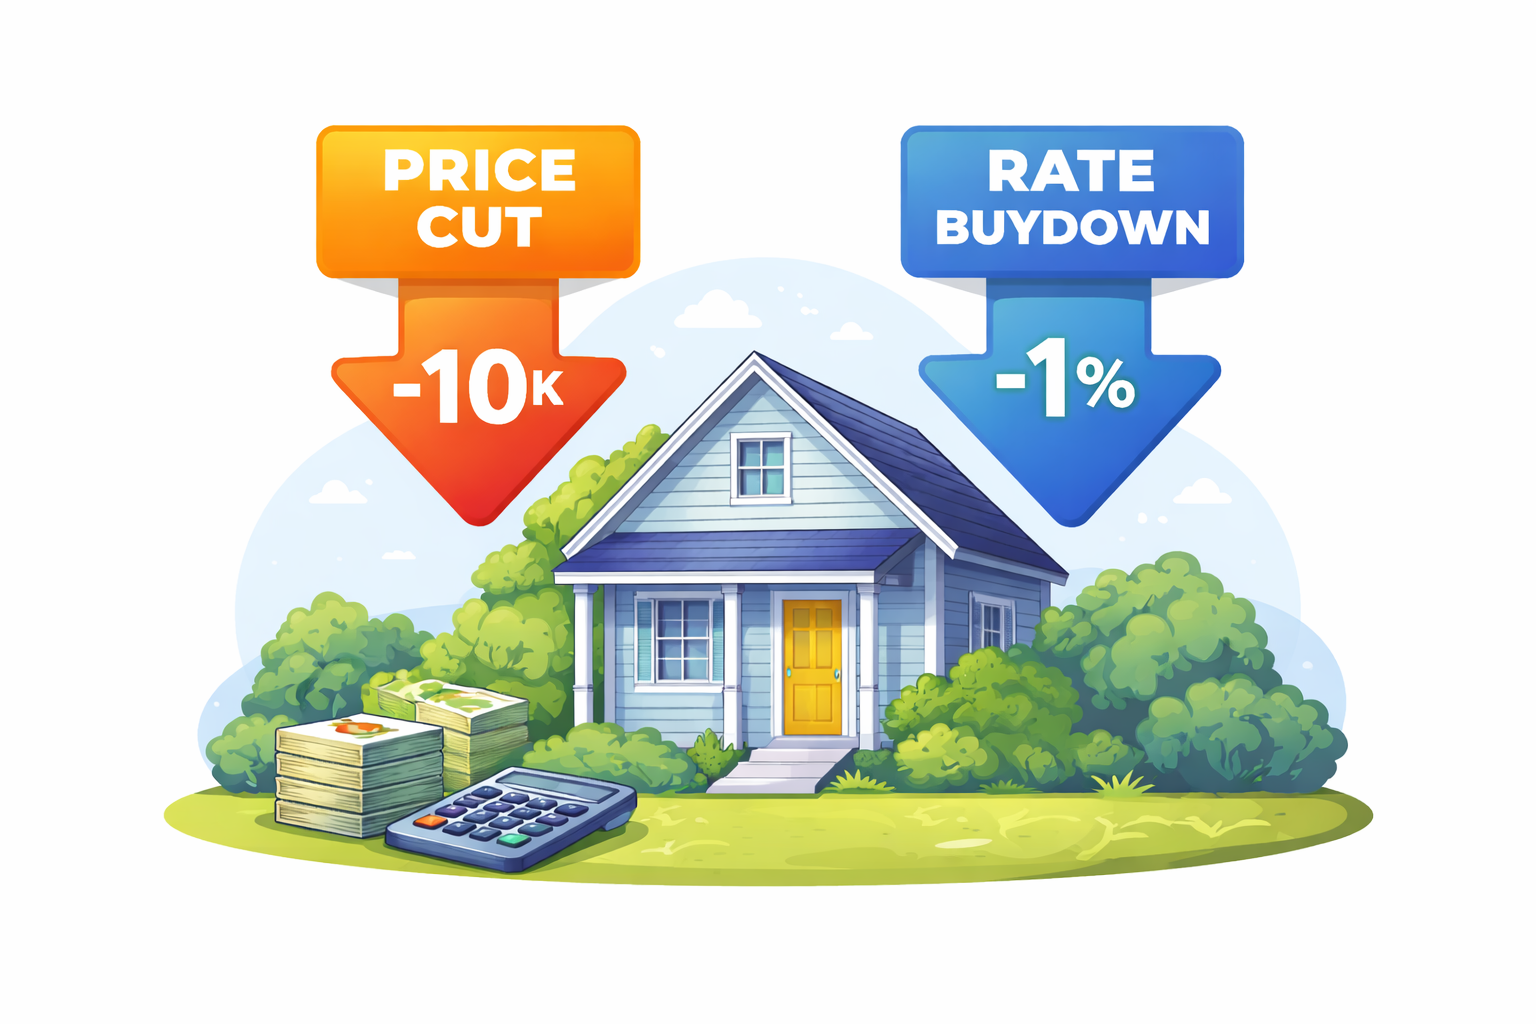
Seller concessions can do more than lower your cash-to-close. When used for a temporary or permanent rate buydown, the same $10K can often reduce your monthly payment more than a $10K price cut.
If you’re shopping homes based on price alone, you’re doing it the hard way. Here’s how to reverse-engineer your home search from a monthly payment you can actually live with.
First-time buyers aren’t buying at 28 anymore. The typical first-time buyer is now 40—and it’s a direct reflection of today’s affordability math, not a personal failure.
Old-school homebuying advice can keep you stuck or push you into a payment that doesn’t fit. Here are the most common “rules” we still hear—and the real-world guidance that works in today’s market.
A clear guide to earnest money: what it is, typical deposit amounts, who holds it, when it’s refundable, and how to protect your funds so your offer stays strong.

Has your mortgage payment jumped—or stepped up? Learn why payments change, from escrow shifts (insurance/taxes) to mortgage insurance removal to temporary buydowns ending, and what to do next.

Avoid the pitfalls most first-time buyers don’t even see coming until it’s too late. Here’s the real advice your future self will thank you for.

Owning a home comes with more than just pride and a mortgage payment. It can also open the door to meaningful tax benefits—from deductions to credits to exclusions. Here’s what to know, without the jargon.
A clear breakdown of what a home equity loan is, how it works, when it makes sense, and the key pros and cons to weigh before borrowing against your home.
Your credit score doesn’t have to be a mystery — or a roadblock. In this post, we break down exactly how credit works, what impacts your score the most, and what steps you can take today to boost it. Whether you’re getting ready to buy a home or just want more financial freedom, this guide gives you the clarity and confidence to take control.
Choosing between a 15-year or 30-year mortgage? This post breaks down the pros and cons of each option—payment differences, interest savings, equity timelines—and helps buyers decide which term fits their goals, lifestyle, and budget.
VA loans are one of the most powerful benefits available to veterans and service members—but most people don’t realize just how much they offer. In this post, we break down the top advantages of VA loans, from zero down payment to flexible credit guidelines, and how to put them to work for your next home purchase or refinance.
Moving before the school year starts? This guide breaks down what families need to know when buying a home on a tight timeline—including how to research school zones, plan backward from your move-in date, and avoid common missteps during the transition.

Learn the real costs of buying a home beyond the down payment. From closing costs to move-in expenses — here's how to budget like a pro.

With high home prices and rising rates, more buyers are teaming up to afford homeownership—especially in pricey markets like Colorado. This blog breaks down the pros, pitfalls, and property types perfect for co-buying with friends or family. From duplexes to ADUs, we’ll walk you through how to do it right—and what to avoid.

Confused by escrow? You’re not alone. This blog breaks down what escrow is, how it works during the homebuying process, and why it’s a key safeguard for your money and peace of mind—before and after closing.

Still think you need 20% down or perfect credit to buy a home? Think again. This post busts the most common myths that keep smart buyers on the sidelines—and shares what’s actually possible in today’s market. If you’re closer to buying than you think, this is the clarity you’ve been waiting for.

Sick of rising rent, slow repairs, or living on someone else’s terms? This post breaks down what renters won’t miss when they finally make the move to homeownership—and the freedom, stability, and financial benefits that come with it. If you’re wondering whether it’s time to buy, start here.

If you’re a veteran, active-duty service member, or surviving spouse, you may qualify for one of the best loan options available: the VA loan. This post breaks down the benefits, busts common myths, and explains how to make the most of your military-earned buying power.

Before you fall in love with a house, get your financing in order. In this article, we explain why pre-approval should always be your first move as a buyer—and how it gives you clarity, credibility, and serious leverage in today’s market.

Wondering what really goes into your mortgage payment? From principal and interest to insurance, taxes, and beyond, this detailed breakdown explains every component so you can plan, budget, and buy smarter—no surprises.

Buying your first home is exciting—but also overwhelming if you don’t know what to expect. This guide breaks down the real deal behind the process, from pre-approval to closing, with honest advice and practical tips to help first-time buyers avoid common pitfalls and feel confident every step of the way.


Straight answers on home loans across Colorado, from Navy Submarine Veteran Jimmy Everetts and the Everetts Lending Team.


