Why Underwriting Asked for That Twice

You're under contract. You sent the lender everything they asked for. Two weeks later they ask for the same bank statement again, plus a letter explaining a deposit you already explained, plus a paystub that didn't exist when you applied.
It feels like disorganization. Often it isn't. There are specific rules underneath most re-asks, and once you can see them the process stops feeling random and starts feeling like a checklist with a clock on it.
One thing to understand before anything else, because it explains most of the friction.
Fannie Mae publishes a Selling Guide that sets the minimum documentation for a conventional loan. Your lender's list will be longer than that minimum, and so will the list from whichever investor ultimately buys your loan. That isn't padding. A lender that delivers a loan the investor later finds thin can be forced to buy it back, so lenders build their standard list above the floor on purpose — and the extra documents are usually the ones that prevent a problem in week six.
So when you see "the guide requires X" below, read it as the floor. The actual list you get is your lender's, it will be somewhat longer, and both are legitimate.
Same goes for the labels. Pre-qualification and pre-approval aren't standardized across lenders — the Consumer Financial Protection Bureau says so directly: "Lenders use the terms 'prequalification' and 'preapproval' differently." Neither is a guaranteed loan offer. Conditional approval, clear to close, prior to doc and prior to funding are internal sequencing language, not fixed terms. If your file is "PTF," the useful question is what specifically is outstanding, not what the label means.
And conditions themselves aren't busywork. Under the Equal Credit Opportunity Act a lender has defined obligations once an application is complete, and a defined process when it isn't. A condition list is the file being formally incomplete — which is why clearing it is the whole job.
Scope: the agency rules below are Fannie Mae's and govern conventional loans. FHA, VA, USDA and loans underwritten to Freddie Mac's guide differ in the details. Your loan officer can tell you which set applies to you.
Expect to be asked for two years of W-2s. The floor is lower than that — for base salary or hourly pay, the guide accepts a verification of employment form, or your most recent paystub and most recent W-2, and says a minimum history isn't required for that income to count. But two years is the standard ask at most lenders, including us, and there are real reasons for it:
If you have the second W-2, send it. Asking for it isn't the lender being difficult.
Variable income. For bonus, commission, overtime and tips, the guide recommends a two-year history. A shorter one can work — but not less than twelve months, and only where positive factors reasonably offset it. That's an underwriter's judgment, not a box you clear at month twelve. One provision added in 2026 helps: where a documented, non-recurring event outside your control temporarily stopped you from earning, the lender may exclude that period from the calculation rather than averaging it in. A documented medical leave doesn't have to drag a commission average down for two years.
Your paystub must be dated no earlier than thirty days before your application date and must show year-to-date earnings. Note the anchor — application date, not closing date. It's a different clock than the one in the next section.
Assets. For a purchase, statements covering the most recent full two-month period — sixty days, or the most recent quarter for accounts reported quarterly. (For a refinance it's one month; the "always two months" you'll read online is purchase-specific.) And a rule that generates a re-ask on its own: if your most recent statement is more than forty-five days older than your application date, the lender should ask for supplemental, bank-generated verification showing the last four digits of the account, the balance, and the date. You didn't do anything wrong. The statement aged out of a window you weren't watching.
Everything has to be legible, complete, and generated by the source — not by you. Documentation has to be computer-generated or typed by your employer, and clearly identify the employer and where the information came from. Paystubs you download yourself are fine. A screenshot, a handwritten note from your boss, or a version you retyped into a Word document is not.
A large deposit is a single deposit exceeding 50% of the total monthly qualifying income for the loan. Not a flat dollar threshold, not cumulative deposits, not a share of your down payment. One deposit, measured against monthly qualifying income. On a purchase, sourcing matters most where the funds are needed for the down payment, closing costs, or reserves — but expect questions about any deposit that stands out, because an unexplained one is exactly what a post-closing audit asks about later.
Resolving one is usually quick. Acceptable documentation includes your written explanation, proof you sold something, or — this is genuinely in the guide — a copy of a wedding invitation supporting receipt of gift funds.
Whether last year's return is required runs off a table with two inputs: when you applied, and when the loan disburses. Most people assume it turns on the application date. It doesn't.
If you applied between mid-April and mid-October and your loan disburses before December 31, the most recent year's return is recommended but not strictly required at the agency floor — the previous year's is also acceptable, and a borrower on a valid extension can often close without filing. The picture flips at year-end. For an application in that same window funding between January and mid-April, the most recent year's return is required, and a tax extension is not permitted.
Practically: if your closing is anywhere near year-end, ask early. A closing that slips from December into January can change what the file needs, and filing an extended return in a hurry is not a small thing.
Two related items:
Scope note: we're describing what a lender needs in a loan file. We are not tax advisors and nothing here is tax advice. Questions about filing, extensions, or what belongs on a return go to your CPA or tax preparer.
Five mechanisms account for most of it.
This is the engine. For all mortgage loans — existing and new construction alike — credit documents must be no more than four months old on the note date.
Three things about that sentence do the damage. "Credit documents" is broad: the guide defines it as credit reports and employment, income, and asset documentation, so the same clock governs your credit report, your paystubs and your bank statements at once. It's four months, not 120 days — four calendar months runs 120 to 123 days depending on which months you're in. And it runs to the note date, not your application date and not the day you sent the file in.
Put that against a Denver timeline. Pre-approved in June, seven weeks of looking, under contract in August, closing in October. The June paystub falls outside a four-month window for a note dated in October, and so does the credit report that went with it. Nothing was lost. Time passed.
Separate from document age, your employment gets verified near the finish line: within ten business days before the note date for a salaried borrower, and for self-employed income, verification the business still exists within 120 calendar days before the note date.
The practical consequence: tell your loan officer before you change jobs, not after. A job change mid-process isn't automatically fatal — the guide says plainly that borrowers who change jobs but earn consistent, predictable income are considered to have a reliable flow of income. But that late verification will find it, and finding it in week one is a very different conversation than finding it two days before closing.
Your file runs through an automated underwriting system that returns a findings report listing what has to be verified. When something material changes, the file is resubmitted and the findings come back — sometimes with different verification messages than last time.
Not every change triggers this. Resubmission is required for specific things: an interest rate increase; new debts or verified income lower than submitted where the recalculated debt-to-income ratio now exceeds 45% or rises three percentage points or more; a permanent rate buydown; income exceeding a product's limits; or cash needed at closing or reserves falling outside what the system required. A rate decrease that isn't from a permanent buydown doesn't trigger it.
So when a new condition appears out of nowhere, something in the file moved. Ask what.
Most lenders re-check credit shortly before closing, and the reason is worth understanding.
The guide doesn't require a new credit report. What it requires is that if a lender does pull one after the initial decision, the loan must be re-underwritten — and that if you disclose new debt or reduced income at any point up to and concurrent with closing that pushes your ratios past the limits, it's re-underwritten regardless. New subordinate financing on the property forces it in all cases. Past the thresholds, the loan isn't eligible for delivery to Fannie Mae at all.
So the lender owns the outcome whether or not it looks. That's exactly why lenders look — catching new debt at day forty is survivable, and catching it at the closing table often isn't.
One footnote, because it's being misread: in late 2025 Fannie added relief from certain representations and warranties for lenders around undisclosed non-mortgage debt on qualifying files. That's an allocation of risk between Fannie and the lender. It excludes mortgage debt, home equity lines and second liens, it doesn't relieve anyone of recalculating your ratios, and it confers exactly zero permission on a borrower to open new credit before closing. Don't buy the truck.
The plainest one. A statement sent as pages one through three of six comes back. Documentation has to be complete and legible, and an underwriter can't treat a document as complete when the document itself says it isn't.
Send the whole PDF. Every time. It's one of the easiest things on this list to get right.
An explanation letter is rarely a rule by itself — it's the cheapest format a lender has for getting your answer into the file in a form an auditor can read two years from now. The underlying question usually does have to be answered: whether new credit was opened, where a deposit came from, why there's a gap in your employment. The letter is just the container.
Scope note: the contract is a legal document and we're describing how its deadlines interact with a loan file, not advising you on it. Your real estate agent can tell you where your deadlines fall and how notices are delivered under the form. Questions about your legal rights, the effect of a notice, or your earnest money go to your own attorney.
If you're buying on the Colorado Real Estate Commission's approved Contract to Buy and Sell Real Estate, your financing runs on named deadlines — and on this form, the name tells you the mechanism.
On the version in use since January 1, 2026, the three that drive a new-loan purchase are the New Loan Application Deadline (you apply by this date), the New Loan Terms Deadline (your right to terminate if the terms aren't satisfactory to you), and the New Loan Availability Deadline (your right to terminate if the loan's availability, after the lender's review and underwriting, isn't satisfactory to you). There is no "Loan Objection Deadline" on the current form — that name is obsolete and you'll still hear it used. The appraisal side runs on the Appraisal Deadline, Appraisal Objection Deadline, and Appraisal Resolution Deadline. Insurance runs on the Property Insurance Termination Deadline — note the suffix; termination is the mechanism.
Why this matters to a file sitting on open conditions: the New Loan Availability Deadline is the one that collides with underwriting, and under the form it operates by notice — a deadline the buyer acts on rather than one that passes on its own. The contract states, in its own capital letters, that if the seller is not in default and does not timely receive the buyer's written notice to terminate, the buyer's earnest money will be nonrefundable, except as otherwise provided elsewhere in the contract, such as the appraisal, title, and survey provisions.
Silence is not neutral under this form. If that date is approaching with conditions unresolved, your loan officer can tell you where the file stands and your agent can tell you what the form requires by when.
And the one that matters most: your tax returns, paystubs and bank statements contain your Social Security number and full account numbers. Don't email them. Ask for a secure upload link and send everything through it — to us or to anyone else you're working with. Email is not a secure channel, and a mortgage file is exactly the kind of thing worth stealing.
Page two looks like a phone bill, so most people file it unread. It's the only page where lenders actually differ — and three rules decide which numbers can move.

A rental gets financed under a different rulebook than the house you live in. Four things change, and the ones that surprise people are worth knowing before you start looking.
The score your lender pulls isn't the one in your banking app. Here's what actually moves in 90 days, what quietly works against you, and the one date on your credit card statement that decides what gets reported.
Family help only counts if it's documented the way your loan program requires. Who can give it, what the gift letter needs, and why the order matters.
Business owners get told they don't make enough all the time — usually because the lender is reading a different number than they are. Here's which one.
Everything you need to know about buying a condo right now and what to look out for.
Buying a home from a family member? A gift of equity may allow an eligible seller to use some of the equity already in the home to help with your down payment and certain closing costs. Learn how it works and why planning ahead matters.
Thinking about buying a home after divorce? Learn what to expect, how divorce may affect your mortgage, and why understanding your options early can help you move forward with confidence.
If you're eligible for a VA loan, should you always use it? Learn why some veterans compare conventional financing, when it may make sense, and why the best mortgage depends on your financial goals—not just your eligibility.

Learn how mortgage contingencies and financing deadlines work, how they may affect earnest money, and what Colorado buyers should consider before limiting an important contract protection.

Should you pay upfront to lower your mortgage interest rate? Learn how mortgage discount points work, how to calculate your break-even point, and when buying points may—or may not—be the right financial decision.
A successful home purchase is about more than finding the right property. Learn why having a thoughtful strategy—and a team that helps you understand your options—can make a meaningful difference throughout the buying process.
Wondering if your mortgage pre-approval expires? Learn how long a pre-approval typically lasts, when updates are needed, and what changes could affect your eligibility.
Many Veterans know the basics of the VA loan program, but few realize just how flexible the benefit can be. Here are some of the most common surprises Veterans discover when they take a closer look at their home loan options.
Most buyers focus on the house itself during a showing, but the factors that determine long-term happiness often have little to do with countertops, paint colors, or staging. Learn how experienced buyers evaluate a home beyond first impressions and what really matters after move-in day.

What is the VA funding fee, why does it exist, and who has to pay it? Learn how VA funding fees work and why they help support one of the strongest loan programs available.
What is a 2-1 buydown, and is it actually worth it? Learn how temporary buydowns work, their pros and cons, and what buyers should consider before using one.
What do homeowners regret most after buying a home? From stretching budgets too far to overlooking long-term lifestyle needs, here are the lessons many buyers wish they knew earlier.
Two buyers can purchase the same home and end up with very different monthly payments. Here’s why—and what it means for your buying strategy.
FHA loans offer flexibility for first-time buyers—but they’re not one-size-fits-all. Learn how they work, their benefits, and what to consider before choosing this option.

First-time homebuyer programs aren’t just about getting into a home—they’re about doing it strategically. Learn how these programs work, who they’re for, and how they can help you buy with confidence.

You’ve built equity in your home—but what does that actually mean for you? Learn the smartest ways to use (or not use) your equity and how to decide what makes sense for your situation.

Thinking about using your 401(k) for a down payment? It’s possible—but it comes with trade-offs. Here’s what homebuyers should understand before tapping into retirement savings.
Your tax refund could be more useful than you think when preparing to buy a home. From boosting your down payment to paying off debt and improving your debt-to-income ratio, here are smart ways buyers use their tax refunds to strengthen their mortgage approval.
Many homebuyers assume student loans automatically prevent them from qualifying for a mortgage. In reality, lenders evaluate several factors beyond just the loan balance. Here’s what actually matters when applying for a home loan with student debt.
If you’ve served our country, you’ve earned more than a handshake. A VA home loan can be one of the most powerful benefits available to eligible veterans, active-duty service members, and surviving spouses. Here’s how it works — and what to know before you use it.
HOA fees are common in the Denver metro area — especially with condos and townhomes. Here’s what buyers should know about costs, rules, financial health, and how HOAs can impact your mortgage approval.
Thinking about upgrading but don’t want to give up your low interest rate? Here’s what happens to your mortgage if you move and keep your current home as a rental — including occupancy rules, qualifying for your next loan, and how rental income can offset your current payment.

Property taxes can feel confusing and stressful, especially when they change. Here’s a clear, no-panic breakdown of how property taxes really work and what homeowners should expect.

From accepted offer to closing table, here’s what really happens during the home-buying timeline — and how the right lender can help you close faster without cutting corners.
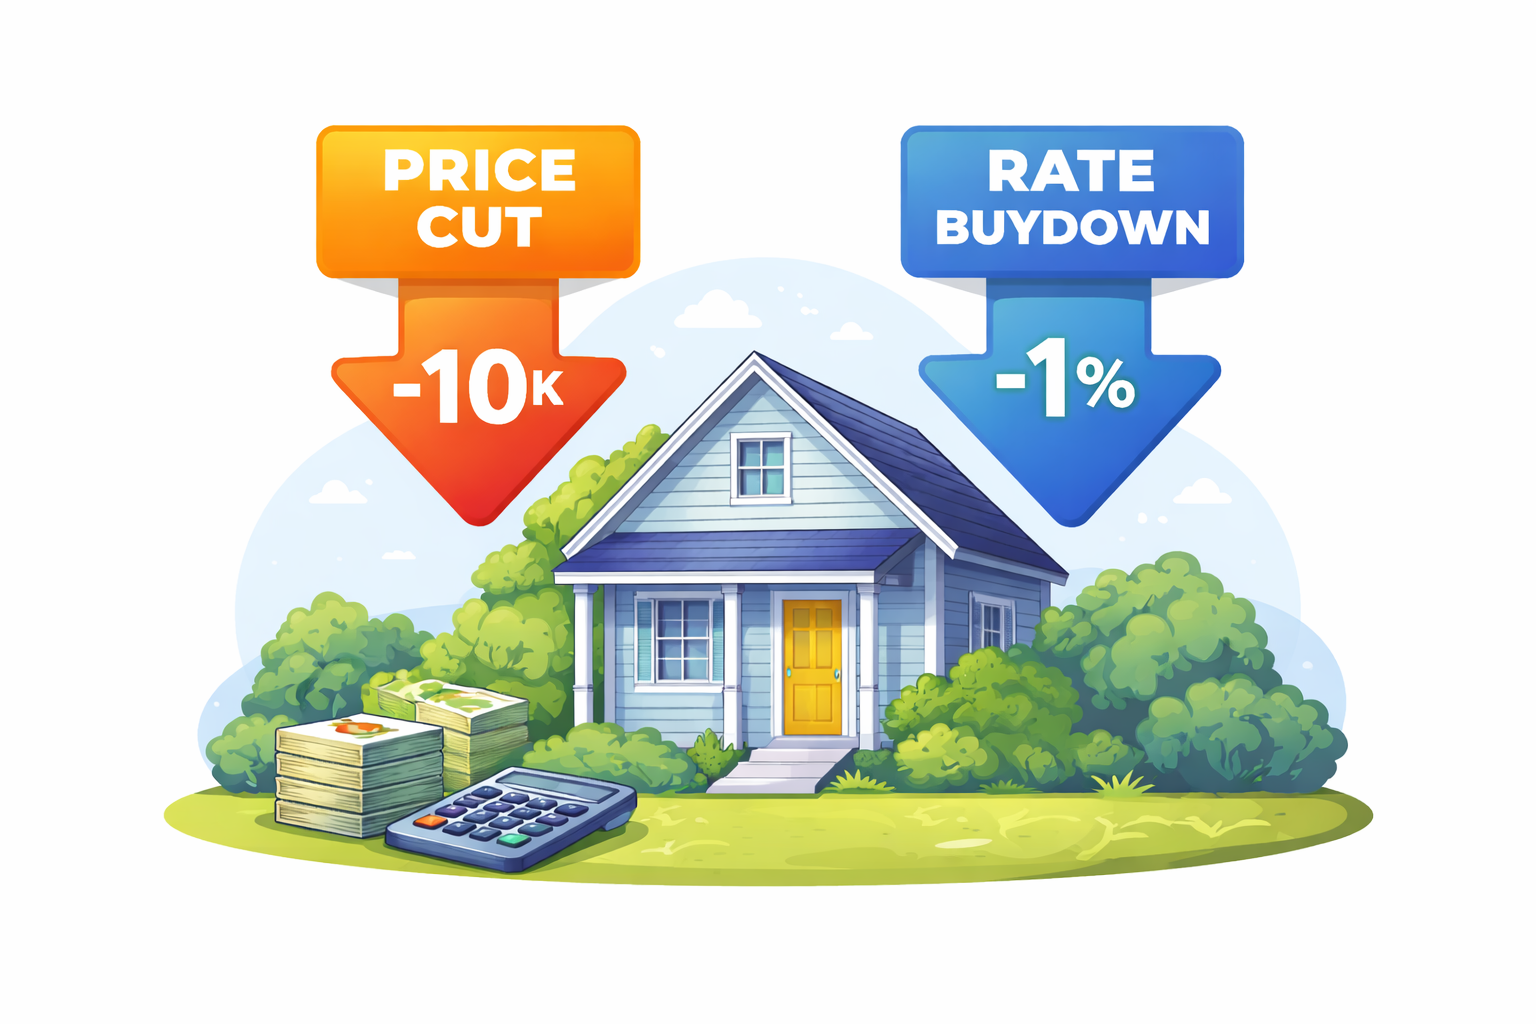
Seller concessions can do more than lower your cash-to-close. When used for a temporary or permanent rate buydown, the same $10K can often reduce your monthly payment more than a $10K price cut.
If you’re shopping homes based on price alone, you’re doing it the hard way. Here’s how to reverse-engineer your home search from a monthly payment you can actually live with.
First-time buyers aren’t buying at 28 anymore. The typical first-time buyer is now 40—and it’s a direct reflection of today’s affordability math, not a personal failure.
Old-school homebuying advice can keep you stuck or push you into a payment that doesn’t fit. Here are the most common “rules” we still hear—and the real-world guidance that works in today’s market.
A clear guide to earnest money: what it is, typical deposit amounts, who holds it, when it’s refundable, and how to protect your funds so your offer stays strong.

Has your mortgage payment jumped—or stepped up? Learn why payments change, from escrow shifts (insurance/taxes) to mortgage insurance removal to temporary buydowns ending, and what to do next.

Avoid the pitfalls most first-time buyers don’t even see coming until it’s too late. Here’s the real advice your future self will thank you for.

Owning a home comes with more than just pride and a mortgage payment. It can also open the door to meaningful tax benefits—from deductions to credits to exclusions. Here’s what to know, without the jargon.
A clear breakdown of what a home equity loan is, how it works, when it makes sense, and the key pros and cons to weigh before borrowing against your home.
Your credit score doesn’t have to be a mystery — or a roadblock. In this post, we break down exactly how credit works, what impacts your score the most, and what steps you can take today to boost it. Whether you’re getting ready to buy a home or just want more financial freedom, this guide gives you the clarity and confidence to take control.
Choosing between a 15-year or 30-year mortgage? This post breaks down the pros and cons of each option—payment differences, interest savings, equity timelines—and helps buyers decide which term fits their goals, lifestyle, and budget.
VA loans are one of the most powerful benefits available to veterans and service members—but most people don’t realize just how much they offer. In this post, we break down the top advantages of VA loans, from zero down payment to flexible credit guidelines, and how to put them to work for your next home purchase or refinance.
Moving before the school year starts? This guide breaks down what families need to know when buying a home on a tight timeline—including how to research school zones, plan backward from your move-in date, and avoid common missteps during the transition.

Learn the real costs of buying a home beyond the down payment. From closing costs to move-in expenses — here's how to budget like a pro.

With high home prices and rising rates, more buyers are teaming up to afford homeownership—especially in pricey markets like Colorado. This blog breaks down the pros, pitfalls, and property types perfect for co-buying with friends or family. From duplexes to ADUs, we’ll walk you through how to do it right—and what to avoid.

Confused by escrow? You’re not alone. This blog breaks down what escrow is, how it works during the homebuying process, and why it’s a key safeguard for your money and peace of mind—before and after closing.

Still think you need 20% down or perfect credit to buy a home? Think again. This post busts the most common myths that keep smart buyers on the sidelines—and shares what’s actually possible in today’s market. If you’re closer to buying than you think, this is the clarity you’ve been waiting for.

Sick of rising rent, slow repairs, or living on someone else’s terms? This post breaks down what renters won’t miss when they finally make the move to homeownership—and the freedom, stability, and financial benefits that come with it. If you’re wondering whether it’s time to buy, start here.

If you’re a veteran, active-duty service member, or surviving spouse, you may qualify for one of the best loan options available: the VA loan. This post breaks down the benefits, busts common myths, and explains how to make the most of your military-earned buying power.

Before you fall in love with a house, get your financing in order. In this article, we explain why pre-approval should always be your first move as a buyer—and how it gives you clarity, credibility, and serious leverage in today’s market.

Wondering what really goes into your mortgage payment? From principal and interest to insurance, taxes, and beyond, this detailed breakdown explains every component so you can plan, budget, and buy smarter—no surprises.

Buying your first home is exciting—but also overwhelming if you don’t know what to expect. This guide breaks down the real deal behind the process, from pre-approval to closing, with honest advice and practical tips to help first-time buyers avoid common pitfalls and feel confident every step of the way.


